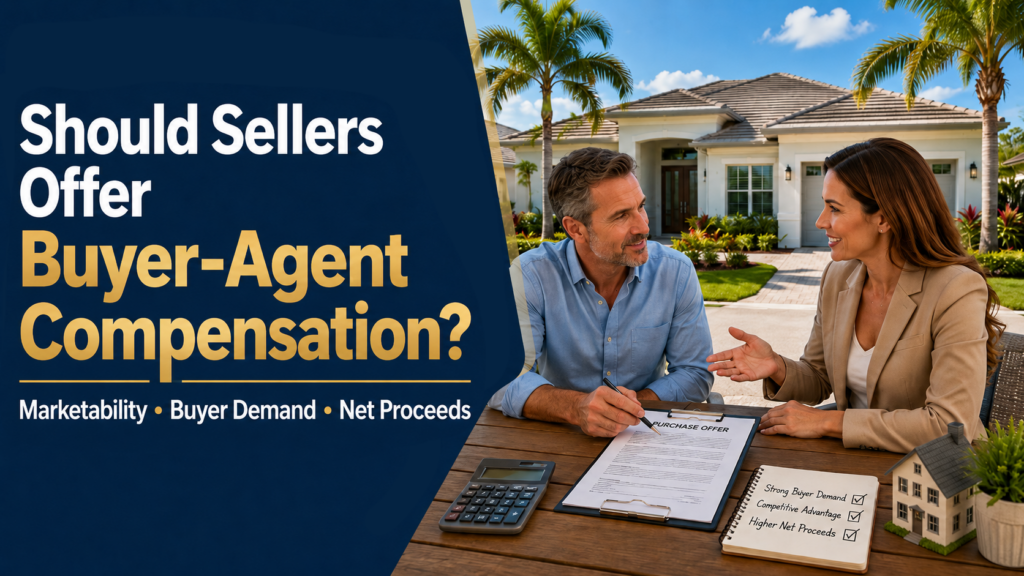
The way buyer-agent compensation is handled has changed, but the seller still has an important strategic choice to make.
Buyer-agent compensation is the fee paid to the real estate professional representing a buyer. Sellers can choose to offer or authorize compensation toward that fee, but compensation is negotiable and offers of compensation are no longer displayed through the MLS.
From an appraisal perspective, commission strategy does not automatically add to or subtract from a property’s market value. What matters is whether the strategy changes buyer demand, contract terms, concessions, marketing time, or ultimately the prices buyers are willing to pay.
How Does This Affect Buyers?
Florida buyers are increasingly sensitive to their total cash required to close, not simply the purchase price. A compensation strategy that reduces an otherwise qualified buyer’s upfront expense may improve a property’s competitive position, while sellers must balance that potential benefit against what they ultimately net from the transaction.
Buyer-Agent Compensation Is Now Part of the Negotiation
Today, compensation should be viewed as another negotiable component of the transaction rather than an automatic or predetermined expense.
Sellers Should Understand:
- Compensation is negotiable.
There is no legally required commission rate, and a seller can decide whether offering buyer-agent compensation makes sense for the property and market. - Offers are handled outside the MLS.
Buyer-broker compensation cannot be advertised through the MLS under current NAR rules, although compensation may still be negotiated through other permitted methods. - Buyers generally know their obligation beforehand.
Buyers working with MLS participants typically enter written agreements establishing their representative’s compensation before touring homes.
Our Appraiser’s Insight:
Commission structure itself is not a property characteristic. Buyer reaction to that structure is what can eventually become measurable market evidence.
Can Offering Compensation Increase Buyer Demand?
Potentially! Particularly when buyers are already stretching to cover down payments, closing expenses, insurance, taxes, and other ownership costs, this can be a good strategy. Here’s Why:
- It Can Reduce Upfront Cash Pressure
If a buyer would otherwise need to personally fund all or part of their representative’s compensation, a negotiated seller-paid amount may preserve cash for closing, reserves, repairs, or moving expenses.
- It May Improve Competitive Positioning
When similar homes are competing for the same buyers, transaction terms can influence which property buyers perceive as offering the better overall opportunity.
- It Can Expand Practical Affordability
A buyer may comfortably afford the mortgage payment yet have limited additional cash available at closing. Compensation negotiations can therefore become part of the buyer’s overall offer strategy.
Our Appraiser’s Insight:
More favorable terms do not automatically mean higher value. But when terms meaningfully influence buyer participation, marketing time, or negotiated prices, the market may eventually reveal that effect through comparable sales.
What About the Seller’s Net Proceeds?
This is where sellers should look beyond commission percentages and focus on the entire transaction. Consider two simplified offers:
| Offer | Purchase Price | Buyer-Agent Compensation | Simplified Amount Before Other Seller Costs |
|---|---|---|---|
| Offer A | $425,000 | $0 | $425,000 |
| Offer B | $435,000 | $10,000 | $425,000 |
(This is an illustrative example only.)
The higher offer does not necessarily produce higher proceeds after compensation and other concessions are considered.
Sellers Should Compare:
- Purchase price
- Requested compensation and other concessions
- The probability that the transaction will actually close
Our Appraiser’s Insight:
The highest contract price and the best financial offer are not always the same thing.
Can Buyer-Agent Compensation Affect Appraised Value?
Not simply because compensation was paid.
As appraisers, we analyze the property and the market evidence surrounding the transaction, including whether unusual financing terms or concessions influenced the sale price. We Pay Attention To:
- Comparable Sale Terms
Was the transaction typical for that market, or did unusual concessions influence the agreed price?
- Buyer Behavior
Are buyers consistently negotiating compensation, closing-cost assistance, rate buydowns, or other terms?
- Market Reaction
Do similar properties with different transaction strategies show measurable differences in sale price, days on market, or seller concessions?
The Important Distinction:
Commission ≠ Property Value
But:
Commission Strategy → Buyer Behavior → Contract Negotiation → Closed Sales → Future Comparable Data
That is where an appraisal connection can eventually develop.
Budget Balancing
Florida real estate is especially sensitive to total ownership affordability.
Buyers frequently must balance the mortgage with substantial expenses such as property insurance, flood insurance where applicable, HOA or condominium fees, taxes, maintenance, and cash needed at closing.
The latest available statewide Florida Realtors data before publication showed that in June 2026, existing single-family homes had a median sale price of $432,000, while sellers received a median 96.1% of their original list price. Inventory stood at approximately 4.5 months’ supply, reinforcing why individual property condition, pricing, location, and transaction terms still matter.
Our Appraiser’s Insight:
In an affordability-sensitive market, transaction flexibility can sometimes improve marketability even when it does not directly increase appraised value.
When Might Offering Compensation Make Sense?
There is no universal answer. But… it May Be Worth Considering When:
- Buyer traffic is weak or marketing time is increasing.
- Comparable properties provide buyers with stronger overall transaction terms.
- The seller can improve the attractiveness of the transaction without sacrificing the desired net proceeds.
A competitively priced property with flexible terms may reach a broader group of financially qualified buyers.
When Might a Seller Choose Not to Offer It Upfront?
A seller may decide that an upfront offer is unnecessary when:
- Demand for the property is exceptionally strong.
- Multiple buyers are competing and presenting different compensation requests.
- The seller prefers to evaluate compensation individually as part of each complete offer.
The important point is that the decision should come from market strategy… not assumptions about what every seller or buyer must do.
Evaluate the Whole Deal
When evaluating an offer, don’t isolate one number. Look at:
Purchase Price
− Buyer-Agent Compensation
− Seller Concessions
− Repair Credits
− Other Seller Costs
= Estimated Net Proceeds
Then consider the strength of the buyer’s financing, appraisal contingency, inspection terms, closing timeline, and likelihood of successfully completing the transaction.
Our Appraiser’s Insight:
Market value reflects what knowledgeable buyers are willing and able to pay under competitive market conditions. The smartest commission strategy is therefore the one that supports exposure and demand without unnecessarily sacrificing the seller’s financial objective.
So… should Seller’s Offer Buyer-Agent Compensation? In today’s Florida real estate market, the question is whether the compensation strategy helps create enough buyer demand, negotiating strength, and transaction certainty to produce the best possible net result.
Ask Our Appraisers
What real estate policy change are you most concerned about right now? (Insurance, flood zones, mortgage rules, HOA/condo regulations, or new development?)
Your question may inspire a future newsletter topic.
Visit www.redefinevalue.com to learn more about our appraisal services, explore more from our blog right here: https://redefinevalue.com/blog-page/, and connect with us for real estate valuation insights across Florida’s Space Coast and beyond.
Follow us on YouTube, Facebook, and Instagram for more appraisal education, market insights, and property value tips.