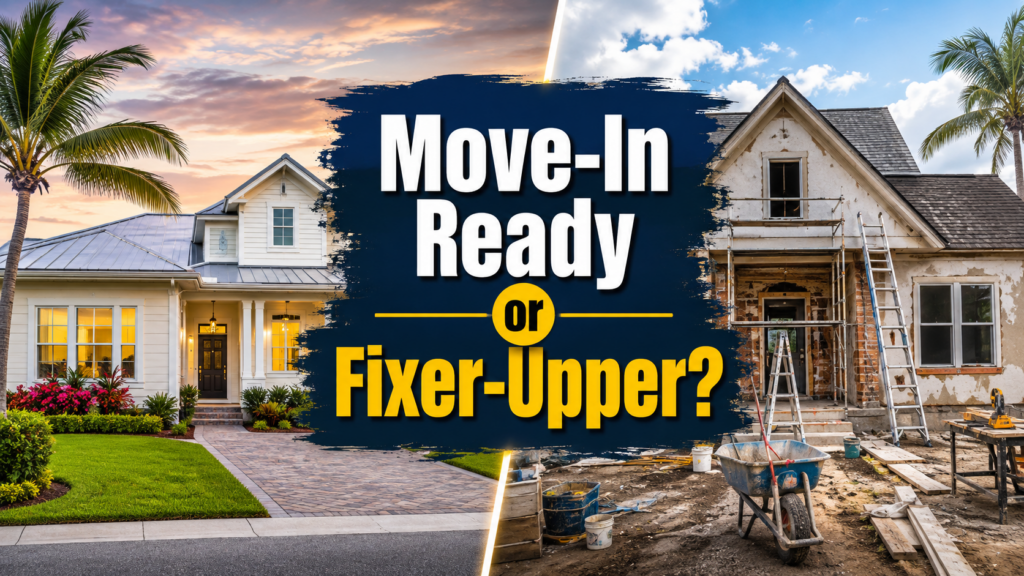
A move-in ready home generally requires little immediate repair or renovation, while a fixer-upper needs improvements before it fully meets a buyer’s expectations or intended use.
From an appraisal perspective, the difference matters because buyers don’t simply compare purchase prices. They also consider the cost, time, financing, risk, and inconvenience required to bring a property up to market standards. In Florida, where construction costs, permitting, insurance requirements, and hurricane-resistant improvements can add complexity, those differences can influence buyer demand and ultimately market value.
A fixer-upper may provide an opportunity to build equity, but renovation dollars don’t automatically translate dollar-for-dollar into appraised value. A move-in ready home may cost more upfront, yet buyers may willingly pay that premium to avoid uncertain expenses, construction delays, and financing complications.
Renovation Cost vs. Contributory Value
One of the biggest mistakes property owners make is assuming:
Renovation Cost = Added Property Value
It doesn’t necessarily work that way. Here are 3 Things to Remember:
- Buyers determine contributory value.
A $60,000 renovation does not automatically increase market value by $60,000. Appraisers analyze comparable sales to determine what buyers actually pay for similar improvements. - Some improvements carry more market weight.
Roofing, HVAC systems, kitchens, bathrooms, functional layouts, and hurricane-related improvements can have stronger buyer appeal when they match neighborhood expectations. - Over-improvement creates risk.
Installing luxury finishes far beyond surrounding homes may produce a beautiful property without producing an equivalent financial return.
💡 Our Appraiser’s Insight:
The question is not: “How much did the renovation cost?” It’s: “How much does the market pay for the improvement?”
Contractor Delays Can Become a Value Problem
A fixer-upper doesn’t just require money. It requires time. Across Florida, renovation timelines can be affected by contractor availability, material delivery, permitting, inspections, weather, and unexpected conditions uncovered once construction begins. Here’s why all of those delays matter:
- Carrying costs continue.
Mortgage payments, taxes, insurance, utilities, HOA fees, and possibly temporary housing continue while improvements are underway. - Investment income may be delayed.
A rental property undergoing months of renovation may generate little or no income during construction. - Market conditions can change.
A renovation planned during one market environment may be completed when mortgage rates, inventory, buyer demand, or comparable sales look different.
💡 Our Appraiser’s Insight:
For investors especially, time is part of renovation cost. A project that runs several months longer than expected can change the profitability equation even when the finished property is worth more.
Financing Can Change the Fixer-Upper Equation
Financing a property needing substantial repairs can be more complicated than purchasing a completed home.
Certain renovation mortgage programs can combine acquisition and improvement costs, but these programs may also involve additional documentation, contractor requirements, renovation plans, escrowed funds, inspections, completion deadlines, and an appraisal based partly on the property’s anticipated completed condition. This can affect value decisions because:
- Not every buyer has the same financing options.
A property requiring extensive work may attract a smaller pool of qualified purchasers. - The appraisal may involve an “as-completed” value.
The appraiser analyzes what the property is expected to be worth after specified improvements… not simply what those improvements cost. - Financing limitations can cap the project.
A buyer may envision $100,000 in renovations but discover that the loan program, appraisal, available cash, or completed value will not support the entire plan.
💡 Our Appraiser’s Insight:
A fixer-upper can look affordable at the asking price while becoming considerably less affordable once the complete acquisition-and-renovation budget is calculated.
Why Florida 🌴Makes the Decision Different
Renovation decisions in Florida carry several considerations that may not be as prominent in other states. Here are 3 Major Factors:
- Wind and storm resistance matter.
Roofs, windows, doors, electrical systems, and structural improvements may affect not only condition but also insurability and buyer perception. - Permits and code compliance matter.
Unpermitted additions or renovations can create appraisal, insurance, resale, and financing complications. - Insurance can change the renovation priorities.
A beautiful kitchen may attract buyers, but an aging roof or other insurability concern can become the more urgent financial issue.
💡 Our Appraiser’s Insight:
Sometimes the improvement buyers value most is not the most glamorous one. Reducing future risk and ownership expense can be highly marketable.
Move-In Ready vs. Fixer-Upper? This is How the Market Reacts to Both
A Move-In Ready Home 🏡 May Offer:
- Less immediate financial uncertainty because major repairs are already completed.
- A larger potential buyer pool because conventional financing and occupancy may be simpler.
- Stronger marketability when buyers are unwilling to take on additional renovation costs after closing.
The trade-off? Buyers may have to pay a premium for convenience and improved condition.
A Fixer-Upper 🛠️ May Offer:
- A lower acquisition price compared with renovated competing properties.
- Potential equity creation when improvements are purchased efficiently and supported by neighborhood demand.
- Customization opportunities that allow an owner to improve functionality rather than pay for someone else’s renovation choices.
The trade-off? Cost overruns, contractor delays, financing restrictions, and over-improvement can quickly reduce the expected profit.
How Can YOU Use This Information Strategically? 🎯
Before Buying or Renovating:
- Build the entire budget.
Calculate purchase price + renovation + financing + insurance + carrying costs + contingency. - Study the neighborhood ceiling.
Determine what renovated homes actually sell for before committing to major improvements. - Get professional input before construction.
A qualified appraiser can help identify which property characteristics buyers have historically rewarded in your particular market.
For an investment property, run the same analysis using rent, vacancy, renovation downtime, operating expenses, and resale potential. The cheapest house is not necessarily the best investment—and the most expensive renovation is not necessarily the most profitable one.
A beautifully renovated home may support a premium when comparable sales demonstrate that buyers are actually paying one.
Likewise, a fixer-upper may require a measurable condition adjustment when the market discounts properties requiring immediate capital expenditures.
Market evidence determines the adjustment… not renovation receipts.
🗝️ Key Takeaway
The better choice is not automatically the move-in ready home or the fixer-upper—it is the property where purchase price, renovation risk, financing, ownership costs, and market-supported value create the strongest overall equation. In Florida real estate, understanding that equation before you buy or renovate can protect your equity, improve profitability, and prevent an expensive project from becoming an appraisal surprise.
Ask Our Appraisers
What real estate policy change are you most concerned about right now? (Insurance, flood zones, mortgage rules, HOA/condo regulations, or new development?)
Your question may inspire a future newsletter topic.
Visit www.redefinevalue.com to learn more about our appraisal services, explore more from our blog right here: https://redefinevalue.com/blog-page/, and connect with us for real estate valuation insights across Florida’s Space Coast and beyond.
Follow us on YouTube, Facebook, and Instagram for more appraisal education, market insights, and property value tips.