For years, home shopping revolved around one big number: the purchase price.
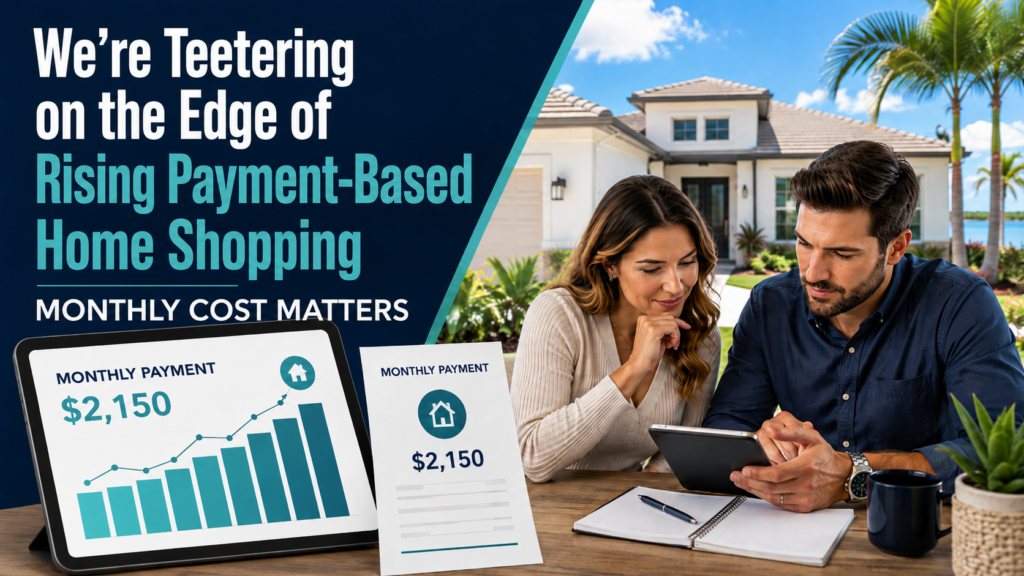
Payment-based home shopping changes that conversation. Instead of asking only, “How much does this house cost?” buyers are increasingly evaluating what the property will cost every month after the mortgage, property taxes, homeowners and flood insurance, HOA or condo fees, utilities, and other recurring expenses are added together.
For property values, this matters because market value depends on what buyers are willing and financially able to pay. When monthly ownership costs rise, purchasing power can fall… even when the asking price stays exactly the same.
Why Is This Such a Big Deal?
A property can be competitively priced and still feel unaffordable once its complete monthly carrying cost is calculated. When enough buyers reach that conclusion, demand, negotiating leverage, marketing time, concessions, and eventually comparable sales can change. In other words: the monthly payment is becoming part of the buyer’s definition of value.
The Mortgage Payment Is Becoming the Starting Line
As of August 6, 2026, the average U.S. 30-year fixed mortgage rate was approximately 6.69%.
At rates near today’s levels, relatively small differences in purchase price, interest rate, or financing terms can produce noticeable differences in monthly payments. Here’s what buyers are comparing:
- Principal + Interest
Two homes separated by $25,000–$50,000 in price can create a meaningful monthly-payment difference. - Rate Buydowns & Seller Concessions
A seller or builder offering financing assistance may make a more expensive property feel more affordable on a monthly basis. - Cash Required vs. Monthly Cost
Buyers may accept a higher purchase price if the financing structure produces a payment they can comfortably carry.
💡 Our Appraiser’s Insight:
Purchase price still matters… but financing conditions influence buyer behavior, and buyer behavior eventually becomes comparable-sales data.
In Florida 🌴, the Mortgage Is Only Part of the Payment
Florida makes payment-based shopping especially important because two similarly priced homes can have dramatically different ownership costs. Here are 3 expenses that can Change the equation:
- Property Insurance
Roof age, wind mitigation, construction type, storm exposure, prior claims, and insurer eligibility can affect premiums. - Flood Insurance
A property’s flood zone, elevation, and individual risk characteristics may create another significant recurring expense. - HOA & Condo Fees
Association dues, reserve funding, insurance expenses, amenities, and special assessments can turn an attractive purchase price into a much larger monthly obligation.
💡 Our Appraiser’s Insight:
Buyers don’t experience these expenses separately. They experience them as one household budget. That means a $400,000 home with lower insurance and association expenses could compete very differently from another $400,000 home carrying significantly higher recurring costs.
Lower Price Does NOT Always Mean Better Affordability 💰
Imagine two Florida properties:
Home A: $425,000
Lower insurance, newer roof, no HOA.
Home B: $399,000
Higher insurance, HOA dues, and greater flood-related costs.
On the listing page, Home B looks cheaper. But after calculating the complete monthly obligation, Home A could potentially be the more affordable property to own. This changes buyer behavior because:
- Buyers may stretch slightly on purchase price to obtain lower recurring expenses.
- Properties with costly insurance, assessments, or HOA obligations may encounter greater price resistance.
- Lower-risk, efficiently operated homes may attract a broader pool of payment-conscious buyers.
That is the essence of payment-based home shopping.
Home Conditions Are Becoming an Affordability Issue Too
Monthly affordability isn’t limited to bills received every month. Buyers are also asking: “What will this house cost me after I move in?” Here are 3 Features that can matter even more:
- Roof, HVAC & Major Systems
Near-term replacement expenses can make an otherwise affordable home financially uncomfortable. - Move-In-Ready Condition
A property requiring fewer immediate repairs reduces the buyer’s expected post-closing cash burden. - Energy Efficiency
Efficient HVAC equipment, insulation, windows, appliances, and other improvements can influence anticipated operating costs.
💡 Our Appraiser’s Insight:
Cost does not automatically equal value. But when buyers consistently pay more for properties offering lower perceived future expenses, that preference can become measurable through market sales.
Monthly Cost Can Eventually Affect Appraised Value 📉
Appraisers don’t simply deduct a homeowner’s insurance premium from a home’s value. We study how the market reacts. We look for evidence of the following:
- Comparable Sales
Are buyers consistently paying more for otherwise similar properties with lower ownership-cost burdens? - Days on Market & Concessions
Are high-cost properties taking longer to sell or requiring larger seller credits? - Buyer Demand
Are certain homes attracting fewer qualified buyers because monthly costs push them beyond affordability limits?
When these patterns become measurable, they may help explain differences among comparable sales and neighborhood pricing. The expense itself isn’t automatically the adjustment… the market reaction to that expense is what matters.
Payment Shopping Could Reshape Florida’s Neighborhood Competition
This shift could become particularly important across Florida because housing costs vary dramatically even within the same metropolitan area. Buyers might increasingly favor:
- Homes with newer roofs, hurricane protection, and lower insurance exposure.
- Communities with manageable HOA fees and financially stable associations.
- Properties offering a better combination of price, taxes, insurance, maintenance, and financing.
This means two neighborhoods with similar home prices may perform very differently if one offers a substantially lower total cost of ownership. Over time, that can affect buyer migration, neighborhood demand, resale liquidity, rental profitability, and future comparable sales.
Sellers Might Need to Market the Payment… Not Just the House
A home’s financial advantages can become part of its competitive position. Before listing, consider documenting the following:
- Insurance Advantages
Wind mitigation reports, newer roof permits, impact protection, and transferable insurance information when appropriate. - Recent Improvements
Roof, HVAC, electrical, plumbing, energy-efficient upgrades, and other improvements that may reduce immediate ownership expenses. - Association Financial Information
Current dues, reserves, recent assessments, and relevant documentation can help reduce buyer uncertainty.
💡 Our Appraiser’s Insight:
A property with a higher asking price may still offer buyers better financial utility if it reduces the expenses waiting for them after closing.
Investors Should Compare Monthly Carrying Cost Against Income
Payment-based analysis becomes even more important for income-producing real estate. Instead of asking only:
“What is my acquisition price?”
The stronger question is:
“What does this property cost me every month compared with what it can realistically earn?”
Focus on These 3 Numbers:
- Realistic market rent.
- Total recurring operating and financing costs.
- Expected net cash flow after reserves and expenses.
Higher taxes, insurance, HOA fees, maintenance, and financing costs can weaken returns even when the acquisition price initially looks attractive. Purchase price gets you into the investment. Monthly performance determines whether the investment works.
Here’s What YOU Should Do Before Buying or Pricing a Florida Property?
Start comparing homes the way many buyers increasingly do: as monthly financial packages rather than standalone prices. Before making a decision:
- Obtain realistic insurance and flood-insurance estimates early.
- Review property taxes, HOA/COA costs, assessments, and major deferred maintenance.
- Compare the complete monthly cost of competing properties—not simply their asking prices.
That analysis may reveal that the “cheaper” property isn’t actually cheaper at all.
KEY TAKEAWAY 🔑
Florida real estate is moving toward a market where buyers aren’t simply asking, “What does this home cost?” They’re asking, “What will this home cost me every month?” Properties that deliver the strongest combination of purchase price, financing, insurance, taxes, condition, and recurring expenses may increasingly win buyer demand… and today’s payment decisions can become tomorrow’s comparable sales and appraised values.
Ask Our Appraisers
What real estate policy change are you most concerned about right now? (Insurance, flood zones, mortgage rules, HOA/condo regulations, or new development?)
Your question may inspire a future newsletter topic.
Visit www.redefinevalue.com to learn more about our appraisal services, explore more from our blog right here: https://redefinevalue.com/blog-page/, and connect with us for real estate valuation insights across Florida’s Space Coast and beyond.
Follow us on YouTube, Facebook, and Instagram for more appraisal education, market insights, and property value tips.